2026 Social Security COLA: What a 3.2% Means for You
Anúncios
The 2026 Social Security Cost-of-Living Adjustment (COLA) of 3.2% is set to impact millions of beneficiaries, influencing retirement planning and financial stability amidst economic shifts.
Anúncios
Understanding the implications of Navigating 2026 Social Security Benefit Adjustments: What a 3.2% COLA Means for Your Retirement Planning is crucial for current and future retirees. This anticipated adjustment will shape financial realities, requiring careful consideration and strategic planning to ensure long-term stability.
Anúncios
Understanding the 2026 Social Security COLA
The Cost-of-Living Adjustment, or COLA, is a vital mechanism designed to help Social Security benefits keep pace with inflation. Each year, the Social Security Administration (SSA) announces a COLA, which translates into an increase in monthly benefits for retirees, disabled individuals, and survivors. This adjustment is not arbitrary; it’s calculated based on specific economic indicators, primarily the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W).
For 2026, the projected 3.2% COLA signals an ongoing effort to maintain the purchasing power of beneficiaries in an evolving economic landscape. This percentage reflects the observed changes in consumer prices, aiming to mitigate the erosion of benefits due to rising costs of living. While any increase is generally welcomed, understanding its practical impact requires a deeper dive into how it interacts with other financial aspects of retirement.
How COLA is Calculated
The calculation of COLA is a precise process, rooted in data collected by the Bureau of Labor Statistics. The CPI-W measures the average change over time in the prices paid by urban wage earners and clerical workers for a market basket of consumer goods and services. Social Security uses the average CPI-W for the third quarter of the current year compared to the third quarter of the previous year to determine the COLA for the upcoming year.
- CPI-W Data: The primary index used for COLA determination.
- Third Quarter Average: Comparison period for year-over-year inflation measurement.
- No COLA in Deflation: If the CPI-W shows no increase, or a decrease, there is no COLA.
This methodology ensures that the adjustment directly reflects the inflationary pressures experienced by a significant portion of the population. A 3.2% increase suggests that consumer prices have risen at a moderate but noticeable rate, necessitating an upward revision of benefits to help beneficiaries maintain their standard of living.
In conclusion, the 2026 Social Security COLA is a direct response to economic inflation, calculated using a standardized index to ensure that beneficiaries’ purchasing power is protected. This 3.2% adjustment is a critical factor for anyone relying on Social Security for their financial well-being, highlighting the need for continuous monitoring of economic trends.
The Direct Impact of a 3.2% COLA on Your Benefits
A 3.2% COLA translates directly into an increase in the monthly Social Security checks received by beneficiaries. While the percentage might seem small, its cumulative effect over a year, and over many years in retirement, can be substantial. For an individual receiving the average Social Security benefit, this adjustment could mean an additional few hundred dollars annually, providing crucial support for daily expenses or allowing for greater flexibility in budgeting.
However, the actual dollar amount of the increase will vary significantly based on an individual’s current benefit level. Those with higher pre-COLA benefits will see a larger monetary increase, while those with lower benefits will experience a smaller, albeit still important, boost. This proportional increase maintains equity across all beneficiaries, ensuring that everyone receives an adjustment relative to their existing entitlement.
Example of Benefit Adjustment
To illustrate, consider a beneficiary currently receiving $1,800 per month. With a 3.2% COLA, their new monthly benefit would be calculated as follows:
- Current Benefit: $1,800
- COLA Percentage: 3.2%
- Increase Amount: $1,800 * 0.032 = $57.60
- New Monthly Benefit: $1,800 + $57.60 = $1,857.60
This example demonstrates how the COLA directly impacts the individual’s income, providing a tangible boost that can help offset rising costs. It’s important for beneficiaries to review their new benefit statements once they become available to confirm their updated payment amounts.
Moreover, the 3.2% COLA also affects other Social Security-related figures, such as the maximum taxable earnings and the earnings limit for those still working while receiving benefits. These adjustments are part of a broader recalibration of the Social Security system to align with economic realities. Understanding these interconnected changes is fundamental for comprehensive retirement planning.
In summary, the 3.2% COLA directly increases monthly Social Security benefits, with the exact dollar amount depending on individual circumstances. This adjustment is designed to help maintain purchasing power, making it a critical component of financial stability for retirees.
Inflationary Pressures and the COLA’s Role in Retirement Planning
Inflation is a persistent economic force that erodes the purchasing power of money over time. For retirees on fixed incomes, even moderate inflation can significantly impact their financial well-being. This is where the Social Security COLA plays a critical role, acting as a buffer against rising costs of living. The 3.2% COLA for 2026 is a direct acknowledgment of these inflationary pressures, aiming to ensure that beneficiaries can continue to afford essential goods and services.
However, it’s important to recognize that the COLA, while helpful, may not always perfectly match an individual’s personal inflation rate. The CPI-W, used for COLA calculations, is a broad measure that reflects the spending patterns of urban wage earners. Retirees often have different spending habits, with a larger proportion of their budget allocated to healthcare and housing, which may experience higher inflation rates than the general consumer price index.
Healthcare Costs and COLA
One of the most significant concerns for retirees is the escalating cost of healthcare. While the COLA helps increase Social Security benefits, it often struggles to keep pace with the rapid growth in medical expenses, prescription drugs, and insurance premiums. This disparity can create a financial squeeze, even with a benefit increase.
- Medicare Premiums: Potential increases in Medicare Part B premiums can offset COLA gains.
- Out-of-Pocket Expenses: Deductibles, co-pays, and uncovered services continue to rise.
- Long-Term Care: Costs for long-term care are a major financial burden not fully addressed by COLA.
Therefore, while the 3.2% COLA is a welcome adjustment, retirees must integrate this information into a broader financial strategy that accounts for specific, often higher, inflation rates in critical spending categories. This holistic approach ensures that retirement planning remains robust and adaptable to economic shifts.
The COLA serves as an essential tool in combating inflation for Social Security recipients. However, its effectiveness is nuanced, requiring retirees to consider personal spending patterns and specific inflationary trends, particularly in areas like healthcare, to fully gauge its impact on their financial future.
Strategic Retirement Planning with the 2026 COLA in Mind
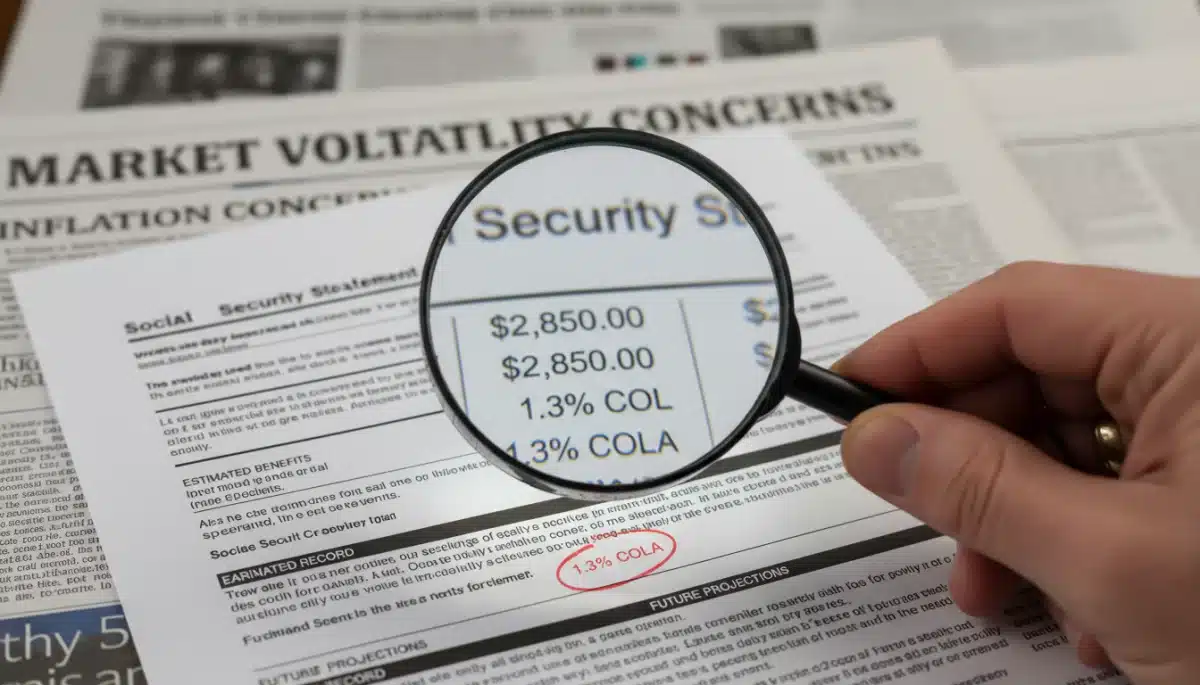
Integrating the 2026 Social Security COLA into your retirement planning requires a proactive and informed approach. While the 3.2% increase provides a boost to income, it’s essential to view it as one component of a larger financial picture. Effective planning involves not only understanding the COLA itself but also assessing how it interacts with other income sources, expenses, and investment strategies.
For many retirees, Social Security benefits form the bedrock of their financial support. A COLA helps preserve the real value of these benefits, but relying solely on these adjustments to maintain living standards can be risky. Diversifying income streams, optimizing investment portfolios, and carefully managing expenditures are equally important to ensure long-term financial security.
Adjusting Your Budget and Spending
With the new COLA, it’s an opportune time to revisit your household budget. The additional funds, even if modest, can be strategically allocated. Consider:
- Covering Rising Costs: Prioritize using the increased benefit to cover any recent increases in essential expenses like groceries, utilities, or transportation.
- Debt Reduction: If you have outstanding debts, even small additional payments can accelerate your path to being debt-free.
- Emergency Fund: Bolstering your emergency savings is always a wise move, providing a safety net for unexpected expenses.
- Discretionary Spending: After covering necessities and savings, any remaining increase can be allocated to discretionary spending, such as hobbies or travel.
This systematic review ensures that the COLA provides tangible benefits, rather than simply being absorbed by unmanaged increases in costs. It empowers retirees to make informed decisions about their money and maintain control over their financial destiny.
Ultimately, strategic retirement planning involves more than just acknowledging the COLA. It requires a holistic view of your finances, adapting your budget, and making informed decisions to maximize the impact of every dollar received, ensuring a comfortable and secure retirement.
Potential Future Social Security Challenges and the COLA
While the 2026 COLA provides a necessary adjustment, the long-term solvency of the Social Security system remains a topic of ongoing discussion and concern. Demographic shifts, such as an aging population and lower birth rates, alongside economic factors, continue to exert pressure on the program’s finances. Understanding these broader challenges is crucial for beneficiaries to anticipate potential future changes and plan accordingly.
The Social Security Trust Funds are projected to be able to pay 100% of scheduled benefits until a certain point, after which they may only be able to pay a reduced percentage if no legislative action is taken. This outlook underscores the importance of staying informed about proposed reforms and advocating for sustainable solutions that protect future generations of retirees.
Legislative Reforms and Their Implications
Various proposals for reforming Social Security have been put forth, each with different implications for benefits and eligibility. These discussions often revolve around:
- Raising the Full Retirement Age: Gradually increasing the age at which individuals can claim full benefits.
- Adjusting the COLA Formula: Revising the way COLA is calculated, potentially using a different inflation index.
- Increasing the Social Security Tax Cap: Applying Social Security taxes to a higher amount of earnings, or even all earnings.
- Benefit Reductions: Implementing across-the-board reductions or means-testing benefits for higher earners.
Each of these potential changes could significantly alter the landscape of future Social Security benefits. While the 2026 COLA is a present reality, retirees and those nearing retirement must remain cognizant of these long-term discussions and their potential impact on future financial planning.
In conclusion, while the 2026 COLA addresses immediate inflationary concerns, the Social Security system faces long-term solvency challenges. Remaining informed about potential legislative reforms and their implications is essential for comprehensive and adaptive retirement planning, ensuring continued financial security for beneficiaries.
Maximizing Your Benefits Beyond the COLA Adjustment
While the 2026 COLA is a welcome increase, maximizing your Social Security benefits involves more than just receiving the annual adjustment. Proactive strategies can significantly enhance your total lifetime benefits and improve your financial outlook in retirement. Understanding these options and making informed decisions can lead to a more secure and comfortable future.
One of the most impactful decisions relates to when you choose to claim your Social Security benefits. While you can start receiving benefits as early as age 62, delaying your claim beyond your full retirement age, up to age 70, can result in substantially higher monthly payments. This strategy is known as delayed retirement credits and can provide a significant boost that far outweighs annual COLA increases over time.
Considerations for Claiming Age
The optimal age to claim Social Security benefits is highly individual and depends on several factors:
- Health and Longevity: If you anticipate a long lifespan, delaying benefits often yields a higher cumulative payout.
- Other Income Sources: If you have sufficient retirement savings or other income, you might be able to afford to delay claiming.
- Spousal Benefits: Married couples have unique strategies to maximize combined benefits, often involving one spouse delaying their claim.
- Work Status: If you plan to continue working, claiming early might lead to a reduction in benefits if you exceed earnings limits.
Thoroughly evaluating these factors, possibly with the help of a financial advisor, can help you make the best decision for your specific circumstances. The difference between claiming at 62 and 70 can amount to tens or even hundreds of thousands of dollars over a typical retirement period.
Furthermore, staying updated on your earnings record through the Social Security Administration’s website is crucial. Errors in your earnings history can lead to lower benefits, so regular reviews can prevent potential shortfalls. Maximizing your benefits is an ongoing process that extends beyond simply receiving the annual COLA, requiring strategic foresight and proactive management.
In conclusion, while the 2026 COLA provides an adjustment, maximizing Social Security benefits involves strategic decisions like optimizing your claiming age and regularly reviewing your earnings record. These proactive steps can significantly enhance your financial security throughout retirement.
Navigating Medicare and Social Security Synergies
For most Social Security beneficiaries, Medicare is an integral part of their retirement planning, and the two programs often interact in complex ways. Understanding the relationship between your Social Security benefits and Medicare premiums is vital, especially when considering the impact of the 2026 COLA. The COLA increase can influence how much you pay for Medicare Part B, due to a provision known as the ‘hold harmless’ rule.
The ‘hold harmless’ provision generally prevents an increase in Medicare Part B premiums from reducing an individual’s net Social Security benefit. However, this rule doesn’t apply to everyone, particularly those new to Medicare, those with higher incomes subject to income-related monthly adjustment amounts (IRMAA), or those whose Part B premiums are paid by a state Medicaid program. For those covered, the 3.2% COLA could mean a larger net increase in their overall income.
Understanding Medicare Part B Premiums
Medicare Part B premiums are typically deducted directly from Social Security benefits. Each year, the Centers for Medicare & Medicaid Services (CMS) announces the standard Part B premium, which can change based on various factors, including healthcare costs and congressional action. For higher-income beneficiaries, IRMAA can significantly increase their Part B premiums.
- Standard Premium: The baseline cost for Medicare Part B.
- Hold Harmless Rule: Protects most beneficiaries from net benefit reductions due to premium increases.
- IRMAA: Income-Related Monthly Adjustment Amounts for higher earners.
- Impact on COLA: COLA can be partially or fully offset by premium increases if not protected by ‘hold harmless’.
Therefore, when you receive notice of your 2026 Social Security benefit, it’s essential to also examine any accompanying information regarding your Medicare Part B premium. The net increase in your disposable income will be the COLA increase minus any increase in your Medicare premium. This integrated perspective is crucial for accurate financial planning.
In conclusion, the synergy between Social Security and Medicare is complex, with the 2026 COLA potentially impacting Medicare Part B premiums. Beneficiaries must understand the ‘hold harmless’ rule and IRMAA to accurately assess their net financial gain and plan accordingly for healthcare costs in retirement.
| Key Aspect | Brief Description |
|---|---|
| 2026 COLA (3.2%) | An increase in Social Security benefits to offset inflation, based on CPI-W. |
| Benefit Impact | Direct increase in monthly payments, proportional to current benefit levels. |
| Retirement Planning | Integrate COLA into budgeting, considering personal inflation rates and other income. |
| Medicare Interaction | COLA can affect Part B premiums, especially for those not under ‘hold harmless’. |
Frequently Asked Questions About the 2026 COLA
The primary purpose of the Social Security Cost-of-Living Adjustment (COLA) is to protect the purchasing power of beneficiaries’ benefits against inflation. It ensures that the value of Social Security payments does not erode over time due to rising costs of goods and services, helping retirees and other beneficiaries maintain their standard of living.
For most beneficiaries, the ‘hold harmless’ provision prevents Medicare Part B premium increases from reducing their net Social Security benefit. However, if you are new to Medicare, have higher income (subject to IRMAA), or your premiums are paid by Medicaid, your Part B premium increase might offset some or all of your 3.2% COLA.
No, the COLA increase is not guaranteed every year. It is only applied if there is an increase in the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) during the third quarter compared to the previous year’s third quarter. If the CPI-W shows no increase or a decrease, there will be no COLA.
To prepare for the 2026 COLA, review your current budget and anticipate how the increased benefit will impact your income and expenses. Consider adjusting your spending or savings plans, especially in light of ongoing inflation in areas like healthcare. Consult your new benefit statement for exact figures.
Yes, there are long-term concerns regarding Social Security’s financial solvency due to demographic shifts. While COLAs are expected to continue, potential legislative reforms could alter how benefits are calculated or distributed in the future. Staying informed about these discussions is important for long-term financial planning.
Conclusion
The 2026 Social Security COLA of 3.2% represents a critical adjustment designed to help beneficiaries maintain their purchasing power amidst ongoing inflationary pressures. While this increase offers a welcome boost to monthly income, its true impact on individual retirement planning requires a nuanced understanding of its interaction with personal budgets, healthcare costs, and broader economic trends. Strategic financial planning, including revisiting budgets, understanding Medicare synergies, and considering long-term Social Security challenges, remains paramount. By proactively engaging with these adjustments, retirees can better navigate their financial landscape and ensure a more secure and stable future.