2026 Housing Market Forecast: When to Refinance for Optimal Savings
Anúncios
Navigating the 2026 housing market forecast is essential for homeowners to strategically determine when to refinance, thereby unlocking optimal savings and improving financial stability.
The landscape of homeownership is constantly evolving, and for many, the decision to refinance a mortgage is one of the most significant financial moves they can make. As we approach 2026, understanding the intricate dynamics of the housing market becomes paramount. This article provides 2026 Housing Market Forecast: Insider Knowledge on When to Refinance for Optimal Savings, offering homeowners crucial insights to navigate potential shifts in interest rates, property values, and economic indicators. Making an informed refinancing decision in the coming years could lead to substantial long-term financial benefits.
Anúncios
Understanding the 2026 Housing Market Dynamics
The 2026 housing market is expected to be influenced by a confluence of economic factors, including inflation, employment rates, and global economic stability. These elements collectively shape consumer confidence and, consequently, demand within the housing sector. Predicting specific movements requires a careful analysis of current trends and potential future policy changes.
Anúncios
Experts are closely watching how central banks manage inflation, as their decisions directly impact interest rates. A more stable economic environment could lead to a more predictable housing market, offering clearer signals for homeowners considering refinancing. Conversely, unexpected economic volatility might introduce challenges, making strategic timing even more critical.
Key Economic Indicators to Monitor
Several key economic indicators will play a pivotal role in defining the 2026 housing market. Understanding these can help homeowners anticipate shifts and prepare for opportune refinancing moments.
- Federal Reserve Policy: Decisions on the federal funds rate directly influence mortgage rates.
- Inflation Rates: Persistent inflation can push interest rates higher, while cooling inflation might lead to reductions.
- Employment Figures: Strong employment typically supports housing demand and price stability.
- Housing Inventory: Supply and demand dynamics significantly impact property values and market competitiveness.
Keeping an eye on these indicators will provide a clearer picture of the overall market health and potential directions for mortgage rates. This proactive approach allows homeowners to be better positioned when considering a refinance.
In conclusion, the 2026 housing market will be a complex interplay of various economic forces. Homeowners need to remain vigilant, tracking key indicators to make well-timed decisions regarding their mortgage refinancing strategies. Proactive monitoring will be essential for capitalizing on favorable market conditions.
Forecasting Interest Rate Movements for 2026
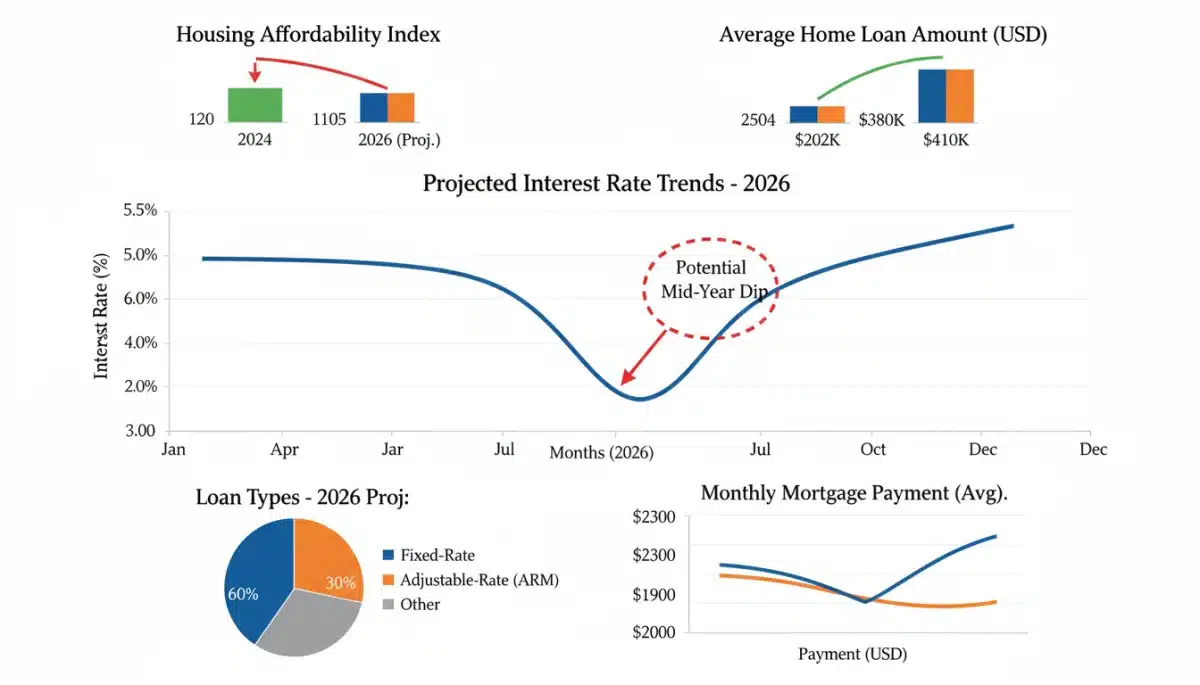
Interest rates are arguably the most critical factor when considering a mortgage refinance. Small fluctuations can translate into significant savings or increased costs over the life of a loan. For 2026, forecasts suggest a period of potential stabilization, following what might be a volatile few years leading up to it.
Many analysts anticipate that the Federal Reserve will continue its data-dependent approach, adjusting rates based on economic performance. This means homeowners should not expect drastic, sudden drops or surges, but rather a more measured response to inflation and employment data. However, geopolitical events or unforeseen economic shocks could always alter this trajectory.
Factors Influencing Mortgage Rates
Several factors beyond the Federal Reserve’s direct control also influence mortgage rates. These include the bond market, investor demand for mortgage-backed securities, and overall lender competition. Understanding these underlying mechanisms can provide a more comprehensive view.
- Treasury Yields: The yield on 10-year Treasury notes often serves as a benchmark for fixed-rate mortgages.
- Market Sentiment: Investor confidence in the economy can drive demand for mortgage bonds, influencing rates.
- Lender Competition: A competitive lending environment can lead to lower rates as institutions vie for borrowers.
- Global Economic Health: International economic conditions can indirectly affect U.S. interest rates.
By monitoring these diverse influences, homeowners can develop a more nuanced understanding of where rates might be headed. This foresight is invaluable when strategizing a refinance, allowing for more informed decisions.
Ultimately, while specific predictions are challenging, the consensus for 2026 leans towards a more stable, albeit potentially still elevated, interest rate environment. Homeowners should focus on identifying periods of relative stability or slight declines to maximize their refinancing benefits.
Identifying Optimal Refinancing Windows
Knowing when to refinance is as crucial as understanding why. The optimal refinancing window typically appears when interest rates drop significantly below your current mortgage rate, or when your financial situation has improved, allowing you to qualify for better terms. For 2026, pinpointing these windows will require a combination of market observation and personal financial assessment.
One common rule of thumb suggests refinancing when you can reduce your interest rate by at least 0.75% to 1.0%. However, this is not a hard and fast rule, as even smaller reductions can be beneficial depending on your loan amount, remaining term, and closing costs. The key is to calculate the break-even point – how long it takes for your savings to offset the refinancing costs.
Signs of a Favorable Refinancing Environment
Several indicators can signal that a favorable refinancing window is opening. Paying close attention to these can help you act decisively.
- Sustained Drop in Interest Rates: A consistent downward trend in mortgage rates is a clear signal.
- Improved Credit Score: A higher credit score can unlock lower rates, even if market rates haven’t changed much.
- Increased Home Equity: Significant equity can lead to better loan-to-value ratios and more favorable terms.
- Reduced Closing Costs: Lenders occasionally offer incentives or lower closing costs, making refinancing more attractive.
By regularly evaluating both market conditions and your personal financial standing, you can proactively identify the best time to refinance. This strategic approach ensures you are not merely reacting to the market but actively seeking opportunities.
The optimal refinancing window in 2026 will likely be a dynamic target, influenced by broader economic shifts and individual circumstances. Homeowners should be prepared to act swiftly when conditions align, ensuring they capture the best possible terms.
Types of Refinance Options for 2026
As the housing market evolves towards 2026, so do the available refinancing options. Understanding the different types of refinances is essential for choosing the one that best aligns with your financial goals. Each option serves a distinct purpose, from reducing monthly payments to consolidating debt or tapping into home equity.
The most common types include rate-and-term refinances, cash-out refinances, and streamline refinances (for government-backed loans like FHA or VA). Your choice will depend on whether you prioritize a lower interest rate, access to cash, or a simpler application process.
Exploring Your Refinance Choices
Each refinancing type comes with its own set of advantages and considerations. A careful evaluation of your current financial situation and future objectives is critical.
- Rate-and-Term Refinance: This is ideal for lowering your interest rate or changing your loan term (e.g., from 30 to 15 years). It doesn’t involve taking out additional cash.
- Cash-Out Refinance: If you need funds for home improvements, debt consolidation, or other large expenses, a cash-out refinance allows you to borrow against your home equity.
- Streamline Refinance: Specifically for FHA or VA loans, this option offers a faster, less paperwork-intensive process, often without the need for a new appraisal or extensive credit checks.
- No-Closing-Cost Refinance: While not a loan type, some lenders offer refinances where closing costs are rolled into the loan or paid by the lender in exchange for a slightly higher interest rate.
Choosing the right refinance option in 2026 will hinge on a thorough understanding of your financial needs and a careful comparison of lender offerings. Consulting with a financial advisor can also provide valuable personalized guidance.
In conclusion, the range of refinance options available in 2026 will cater to various homeowner needs. By understanding the nuances of each, you can select the most appropriate path to optimize your financial situation.
Calculating Refinance Costs and Benefits
Refinancing a mortgage is not without costs, and a crucial step in the decision-making process is to accurately calculate these expenses against the potential benefits. Ignoring closing costs, appraisal fees, and other associated charges can lead to a less favorable outcome than anticipated. For 2026, these costs will likely remain a significant consideration.
Typical refinancing costs can range from 2% to 5% of the loan principal. These can include application fees, loan origination fees, title insurance, attorney fees, and appraisal fees. It is essential to get a detailed breakdown from potential lenders to ensure full transparency.
Strategies for Evaluating Refinance Viability
To determine if refinancing is truly beneficial, a methodical approach to cost-benefit analysis is required. This involves more than just looking at the new interest rate.
- Break-Even Point Calculation: Divide total closing costs by your monthly savings to determine how many months it will take to recoup your investment.
- Long-Term Savings Projection: Calculate the total interest saved over the life of the new loan compared to your current one.
- Impact on Monthly Cash Flow: Assess how the new payment will affect your budget, especially if you are extending the loan term.
- Credit Score Impact: Understand that applying for a new loan can temporarily lower your credit score.
By meticulously calculating these factors, homeowners can make an informed decision that goes beyond a superficial glance at interest rates. A thorough analysis ensures that refinancing truly translates into optimal savings.
Ultimately, a successful refinance in 2026 will depend on a clear understanding of all associated costs and a realistic projection of long-term benefits. This diligent calculation is key to avoiding unforeseen financial pitfalls.
Preparing Your Finances for Refinancing in 2026
Even with favorable market conditions in 2026, a successful refinance hinges on your personal financial preparedness. Lenders will assess your creditworthiness, debt-to-income ratio, and employment stability. Taking proactive steps now can significantly improve your chances of securing the best possible rates and terms.
Start by reviewing your credit report for any inaccuracies and working to improve your credit score. Reducing outstanding debt and building up savings can also present you as a less risky borrower, which often translates to better loan offers.
Steps to Enhance Your Refinance Eligibility
There are concrete actions you can take to strengthen your financial profile before applying for a refinance. These steps can make a considerable difference in the terms you are offered.
- Improve Credit Score: Pay bills on time, reduce credit card balances, and avoid opening new credit lines.
- Lower Your Debt-to-Income Ratio: Pay down existing debts, especially high-interest ones, to demonstrate financial responsibility.
- Gather Essential Documentation: Have recent pay stubs, tax returns, bank statements, and current mortgage statements readily available.
- Build an Emergency Fund: A healthy savings account signals financial stability to lenders.
By diligently preparing your finances, you not only increase your eligibility for a refinance but also position yourself to negotiate more effectively for favorable rates and terms. This proactive approach is a cornerstone of smart financial management.
In summary, personal financial preparation is just as critical as market timing for a successful refinance in 2026. By focusing on credit health, debt management, and documentation, homeowners can significantly enhance their refinancing prospects.
| Key Aspect | 2026 Refinance Strategy |
|---|---|
| Market Forecast | Monitor Fed policy, inflation, and employment for rate stability. |
| Interest Rates | Look for sustained drops or periods of stabilization below current rates. |
| Refinance Types | Evaluate rate-and-term, cash-out, or streamline options based on goals. |
| Financial Readiness | Improve credit score and reduce debt-to-income ratio for better terms. |
Frequently Asked Questions About 2026 Refinancing
The primary indicators include a sustained drop in prevailing interest rates, an improvement in your personal credit score, an increase in your home equity, and potentially lower closing costs offered by lenders. Monitoring these factors concurrently will provide the best timing signals for homeowners.
While a 0.75% to 1.0% drop is a common guideline, even smaller reductions can be worthwhile. It depends on your current loan amount, remaining loan term, and the total closing costs. Always calculate your break-even point to ensure the savings outweigh the expenses.
Yes, a cash-out refinance is expected to remain a viable option in 2026, especially for homeowners with significant home equity. Its attractiveness will depend on interest rates and your need for funds for purposes like home improvements or debt consolidation. Always consider the long-term implications.
Inflation significantly influences mortgage rates. If inflation remains high, the Federal Reserve might keep interest rates elevated, making refinancing less appealing. Conversely, cooling inflation could lead to rate reductions, opening up better refinancing opportunities. Monitoring inflation reports is key.
To prepare, focus on improving your credit score by paying bills on time and reducing debt. Lower your debt-to-income ratio, gather necessary financial documents, and build an emergency fund. These actions will strengthen your financial profile and increase your chances of securing favorable refinance terms.
Conclusion
Navigating the 2026 housing market for optimal refinancing requires a blend of keen market observation and diligent personal financial preparation. While specific predictions can be elusive, understanding the underlying economic indicators, interest rate forecasts, and various refinance options empowers homeowners to make strategic decisions. By meticulously calculating costs versus benefits and strengthening your financial profile, you can position yourself to capitalize on favorable market conditions, ultimately securing significant long-term savings on your mortgage. Proactive engagement with market trends and personal finance will be the cornerstone of successful refinancing in the coming years.