Medicare Part B Premiums 2026: 5% Increase Impact
Anúncios
The anticipated 5% increase in Medicare Part B premiums for 2026 will significantly impact beneficiaries’ healthcare budgets, necessitating proactive financial planning and understanding of the new cost structure.
Anúncios
As 2026 approaches, many Americans relying on Medicare for their healthcare needs are beginning to evaluate the potential financial shifts ahead. The news of an anticipated 5% increase in Medicare Part B premiums for 2026 raises crucial questions about personal healthcare budgets and long-term financial planning for seniors and individuals with disabilities.
Anúncios
Decoding the 2026 Medicare Part B Premium Increase
The annual adjustment to Medicare Part B premiums is a routine but often impactful event for millions of beneficiaries. These adjustments are driven by a complex interplay of factors, including the rising costs of healthcare services, prescription drug expenditures, and broader economic trends. For 2026, a projected 5% increase signals a need for beneficiaries to reassess their financial strategies.
Understanding the rationale behind these increases is crucial. The Centers for Medicare & Medicaid Services (CMS) is tasked with ensuring the program’s solvency while adapting to an evolving healthcare landscape. This often means balancing the need for comprehensive coverage with the realities of healthcare inflation and the utilization of services. The 5% figure is not arbitrary; it reflects careful calculations based on projections of future medical spending and the overall financial health of the Medicare trust funds.
Factors Influencing Premium Adjustments
Several key elements contribute to the annual determination of Medicare Part B premiums. These are not static and can fluctuate significantly year over year, making future projections a challenging but necessary exercise for policymakers.
- Healthcare Spending Trends: Overall increases in healthcare utilization and the cost of medical procedures, hospital stays, and outpatient services directly impact Part B expenditures.
- Prescription Drug Costs: The rising price of new and existing prescription medications, particularly specialty drugs, often places upward pressure on Part B premiums.
- Medical Technology Advancements: While beneficial for patient care, new diagnostic tools and treatment modalities can be expensive, contributing to higher program costs.
- Demographic Shifts: An aging population means more beneficiaries are relying on Medicare, which can strain the program’s financial resources if not managed effectively.
In essence, the 2026 increase is a response to the dynamic nature of the U.S. healthcare system. It’s a mechanism to ensure that Medicare can continue to provide essential coverage, but it undoubtedly places an additional financial burden on those who depend on it most. Beneficiaries should prepare for these changes by reviewing their current budgets and exploring potential avenues for financial mitigation.
Who Will Be Affected by the 5% Increase?
The 5% increase in Medicare Part B premiums for 2026 will have a broad impact across various beneficiary groups, though the degree of impact may vary based on income levels and other factors. Generally, all individuals enrolled in Medicare Part B will see an increase in their monthly premiums. However, for some, particularly those with higher incomes, the proportional increase could feel more significant due to existing surcharges.
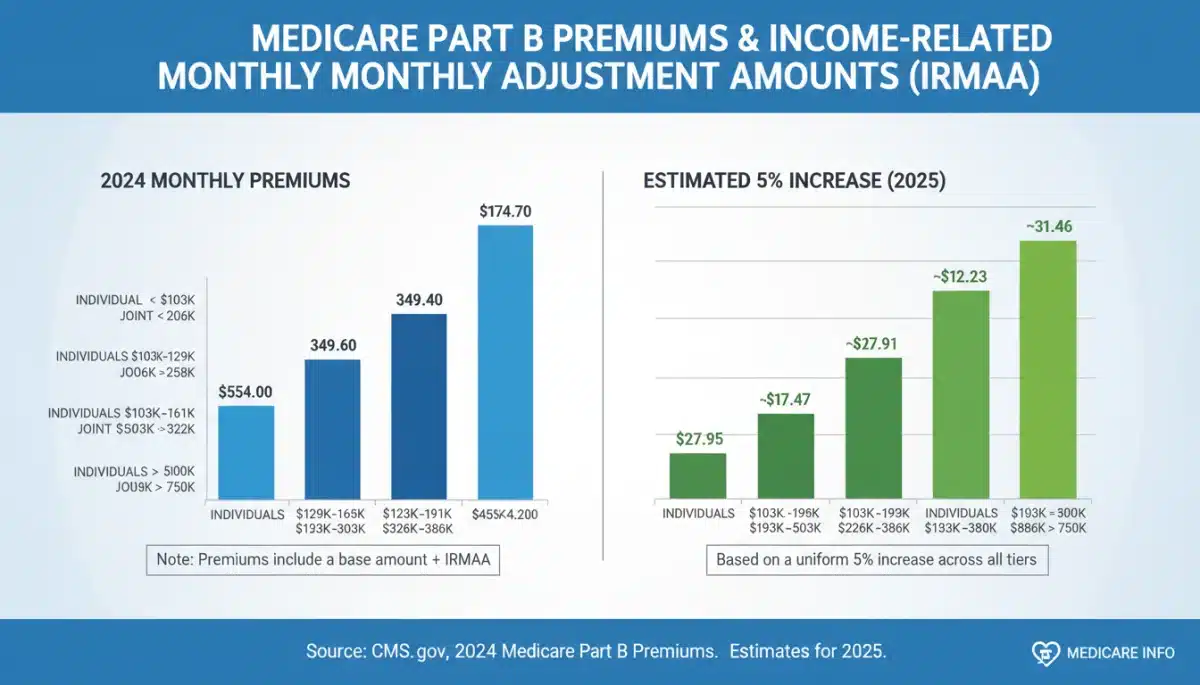
Medicare Part B premiums are not a flat rate for everyone. The standard premium applies to most beneficiaries, but individuals with higher modified adjusted gross incomes (MAGI) pay an Income-Related Monthly Adjustment Amount (IRMAA). This means that wealthier beneficiaries pay a higher premium, and a 5% increase will apply to their already elevated rates, leading to a larger absolute dollar increase.
Understanding Income-Related Monthly Adjustment Amounts (IRMAA)
IRMAA is a critical component of Medicare Part B costs for many. It’s determined by your MAGI from two years prior. For instance, your 2026 IRMAA will be based on your 2024 income. This system ensures that those with greater financial capacity contribute more to the Medicare program.
- Income Thresholds: IRMAA tiers are set annually, and crossing a threshold can significantly increase your premium. A 5% increase will apply to whatever tier you fall into.
- Tax Planning Implications: Understanding how your income impacts IRMAA is vital for tax planning, as certain income-generating activities can push you into a higher premium bracket.
- Appealing IRMAA Decisions: In some cases, beneficiaries can appeal an IRMAA determination if their income has significantly decreased due to life-changing events such as marriage, divorce, or work stoppage.
Even for those not subject to IRMAA, a 5% hike represents a direct reduction in disposable income. It’s essential for all beneficiaries to factor this upcoming change into their financial planning, whether they are on a fixed income or have other sources of revenue. Proactive budgeting and exploring all available resources can help cushion the impact of these increased costs.
Strategies to Mitigate the Impact on Your Healthcare Budget
Facing a 5% increase in Medicare Part B premiums can be daunting, but there are several proactive strategies beneficiaries can employ to help manage their healthcare budgets. Effective financial planning and a thorough understanding of available options are key to minimizing the financial strain.
One primary strategy involves reviewing your overall Medicare coverage. For some, switching from Original Medicare to a Medicare Advantage (Part C) plan might offer a different cost structure, potentially including lower Part B premiums or comprehensive benefits that offset other out-of-pocket expenses. However, it’s crucial to compare plan benefits, networks, and potential limitations carefully before making such a switch.
Exploring Supplemental Coverage Options
Many beneficiaries opt for supplemental coverage to help manage out-of-pocket costs not covered by Original Medicare. These options can significantly reduce financial surprises, especially with rising Part B premiums.
- Medigap Policies: These plans help cover deductibles, co-payments, and co-insurance that Original Medicare doesn’t. A good Medigap plan can provide predictability in your healthcare spending.
- Medicare Advantage Plans (Part C): These all-in-one plans often include Part A, Part B, and typically Part D (prescription drug) coverage. Many also offer additional benefits like vision, dental, and hearing.
- Employer-Sponsored Retiree Health Plans: If you are retired and have access to a former employer’s health plan, it might coordinate with Medicare to provide comprehensive coverage at a potentially lower cost.
Beyond supplemental insurance, beneficiaries should also explore state and federal assistance programs. Medicaid, Medicare Savings Programs (MSPs), and the Extra Help program for prescription drug costs can provide significant financial relief for eligible individuals. These programs can help cover premiums, deductibles, and co-payments, making healthcare more affordable. It’s always advisable to consult with a financial advisor or a Medicare counselor to assess your specific situation and identify the best strategies for your individual needs.
The Role of Healthcare Policy and Future Outlook
The projected 5% increase in Medicare Part B premiums for 2026 is not an isolated event but rather a reflection of ongoing trends and policy decisions within the broader U.S. healthcare system. Understanding the larger context of healthcare policy is essential for appreciating why these adjustments occur and what the future might hold for Medicare beneficiaries.
Policymakers continually grapple with the challenge of maintaining Medicare’s solvency while ensuring access to quality care for a growing senior population. This involves navigating complex issues such as inflation in medical costs, the development of expensive new treatments, and the demographic shift towards an older populace. The annual premium adjustments are one of the mechanisms used to balance these competing demands.
Looking ahead, several legislative and administrative initiatives could influence future Medicare Part B premiums. Efforts to control prescription drug prices, promote value-based care models, and enhance preventive services could all play a role in moderating cost increases. However, the exact impact of these initiatives often takes time to materialize and can be subject to political and economic shifts.
Potential Policy Reforms and Their Impact
- Prescription Drug Price Negotiation: Policies allowing Medicare to negotiate drug prices directly could lead to lower costs, potentially impacting Part B premiums.
- Preventive Care Expansion: Greater emphasis on preventive care and chronic disease management might reduce the need for more expensive interventions down the line.
- Alternative Payment Models: Shifting from fee-for-service to models that reward quality and efficiency could help control overall healthcare spending.
While the 5% increase for 2026 is a certainty for now, the long-term outlook for Medicare Part B premiums remains subject to ongoing policy debates and healthcare innovations. Beneficiaries and their families should stay informed about these developments, as they can directly influence future healthcare costs and access to services. Engaging with advocacy groups and staying updated on legislative proposals can also be beneficial in understanding the evolving landscape.
Understanding Your Medicare Statement and Billing
Navigating your Medicare statements and understanding the billing process can be confusing, but it’s a crucial step in managing your healthcare budget, especially with the upcoming 5% increase in Medicare Part B premiums for 2026. Familiarizing yourself with these documents can help you identify errors, track your spending, and ensure you’re only paying what you owe.
Your Medicare Summary Notice (MSN) is a key document that provides a summary of all services and supplies billed to Medicare during a specific period. It’s not a bill, but it shows what Medicare paid and what you might owe. For Part B premiums, you’ll typically receive a separate bill if you’re not having premiums deducted directly from your Social Security benefits, or the new amount will simply be reflected in your benefit reduction.
Key Elements of Your Medicare Statement
When reviewing your MSN or any billing statement related to Medicare Part B, pay close attention to the following details:
- Service Dates: Ensure the dates of service match when you actually received care.
- Provider Information: Verify that the healthcare providers listed are indeed the ones you visited.
- Services Rendered: Check that the services described align with the care you received.
- Charges and Payments: Compare the amount billed by the provider with what Medicare approved and paid, and note your remaining responsibility.
If you have your Part B premiums deducted from your Social Security, Railroad Retirement Board, or Office of Personnel Management benefits, the increase will automatically be reflected in your monthly benefit statement. If you pay your premiums directly, you will receive a bill from Medicare. It’s important to review these statements carefully to ensure the new premium amount is correctly applied and to understand any changes to your total out-of-pocket costs. If you find any discrepancies, contact Medicare or your provider immediately to resolve them.
Resources and Support for Medicare Beneficiaries
With the impending 5% increase in Medicare Part B premiums for 2026, many beneficiaries will be seeking reliable information and support to navigate these changes. Fortunately, numerous resources are available to help individuals understand their options, manage costs, and make informed decisions about their healthcare.
The official Medicare website (Medicare.gov) is an invaluable starting point. It offers comprehensive information on all aspects of Medicare, including detailed explanations of Part B premiums, coverage rules, and how to find plans. You can also access your personal Medicare account to review your claims, statements, and other important information. This platform is regularly updated with the latest policy changes and cost details.
Key Support Organizations and Programs
Beyond the official Medicare website, several organizations and programs offer personalized assistance and financial aid for beneficiaries struggling with healthcare costs.
- State Health Insurance Assistance Programs (SHIPs): These programs provide free, unbiased counseling to Medicare beneficiaries and their families on a wide range of topics, including understanding premiums, comparing plans, and enrolling in assistance programs.
- Medicaid: For low-income individuals, Medicaid can help cover Part B premiums and other medical expenses. Eligibility varies by state, so it’s essential to check your state’s specific requirements.
- Medicare Savings Programs (MSPs): These state programs help pay for Medicare Part A and Part B premiums, deductibles, coinsurance, and copayments for eligible individuals.
- Extra Help (Low-Income Subsidy): This federal program helps people with limited income and resources pay for prescription drug costs under Medicare Part D.
Don’t hesitate to reach out to these resources. The financial implications of a premium increase can be significant, and these programs are designed to provide a safety net and expert guidance. Staying informed and utilizing available support systems can make a substantial difference in managing your healthcare budget effectively in 2026 and beyond.
| Key Aspect | Brief Description |
|---|---|
| Premium Increase | Medicare Part B premiums are projected to increase by 5% in 2026, impacting all beneficiaries. |
| IRMAA Impact | Higher-income beneficiaries pay Income-Related Monthly Adjustment Amounts (IRMAA), amplifying the 5% increase. |
| Mitigation Strategies | Explore Medigap, Medicare Advantage, and assistance programs to manage rising costs effectively. |
| Available Resources | Utilize Medicare.gov, SHIPs, and federal programs for information and financial support. |
Frequently Asked Questions About Medicare Part B in 2026
The 5% increase in Medicare Part B premiums for 2026 is driven by rising healthcare costs, including prescription drugs, increased utilization of medical services, and advancements in medical technology, all contributing to the program’s overall expenses.
Your specific premium will be communicated by Medicare, usually through a notice or by reflecting the change in your Social Security benefit statement. You can also check Medicare.gov or contact Medicare directly closer to 2026.
Yes, you can explore options like Medicare Advantage plans, Medigap policies, and various state and federal assistance programs such as Medicare Savings Programs (MSPs) or Medicaid, depending on your income and resources.
IRMAA (Income-Related Monthly Adjustment Amount) means higher-income beneficiaries pay an additional amount on top of the standard Part B premium. The 5% increase will apply to your total premium, including any IRMAA, based on your 2024 income.
For personalized assistance, contact your State Health Insurance Assistance Program (SHIP), visit Medicare.gov, or consult with a trusted financial advisor specializing in retirement and healthcare planning. These resources offer free and unbiased guidance.
Conclusion
The anticipated 5% increase in Medicare Part B premiums for 2026 marks a significant adjustment for millions of Americans. It underscores the dynamic nature of healthcare costs and the ongoing efforts to sustain the Medicare program. While this change presents a financial challenge, understanding the underlying reasons, identifying personal impacts, and proactively exploring mitigation strategies are crucial steps for every beneficiary. By leveraging available resources, considering supplemental coverage, and staying informed about policy developments, individuals can navigate these changes more effectively and maintain control over their healthcare budgets in the years to come.